Client Money, Clearer Lines: Belfast’s Payments Firms and the New Safeguarding Test
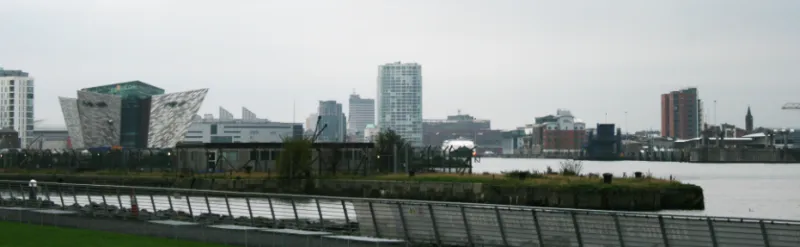
Photo: Davidwiltonone, CC BY-SA 3.0, via Wikimedia Commons
For Belfast’s payments and e-money startups, safeguarding has long sat somewhere between operations and compliance. It is discussed in diligence, checked by auditors and monitored by sponsor banks, but it rarely shapes the product story. That is changing. The FCA’s tougher expectations for how payments and e-money firms hold customer funds are making client-money controls a board-level question, a merchant-diligence issue and, for some younger firms, a brake on growth.
The shift is not simply about putting more money in a separate account. It is about being able to prove, at short notice, where every pound of relevant funds sits, who controls it, how it is reconciled and what happens if the firm fails. For a cluster built on lean teams and fast launches, that is a demanding standard. It is also an opportunity for Northern Ireland to differentiate on something less glamorous than product innovation: airtight client-money governance.
Why the bar has moved
The direction of travel is clear. Regulators want payments and e-money firms to treat safeguarding as a live control system rather than a static legal arrangement. In practice, that means robust segregation of relevant funds, clear trust documentation, frequent reconciliation, independent oversight and credible wind-down planning. Firms are expected to know not only that funds are safeguarded, but that they can evidence the claim across multiple accounts, currencies and legal entities.
The FCA has also been tightening its expectations around acknowledgement letters from safeguarding banks, diversification of safeguarding arrangements and resolution packs. The message is that client money should remain identifiable and accessible if a firm enters insolvency or an orderly wind-down. For startups, the operational implications are significant. Reconciliation that was once a monthly spreadsheet exercise becomes a daily control. Bank relationships that were once informal become contractual and evidence-based. Governance that was once delegated to a finance manager becomes a board responsibility.
The pressure points in Belfast
The challenge is particularly acute in a payments cluster dominated by young firms. Many are building multi-currency products for UK merchants, handling cross-border flows between Great Britain, Northern Ireland and the Republic of Ireland, or supporting e-commerce platforms with complex settlement cycles. Each additional currency, counterparty and legal entity adds a layer of reconciliation and documentation.
Sponsor banks and safeguarding institutions are also applying more scrutiny. A Belfast startup may find that its banking provider wants clearer evidence of controls before opening additional accounts or extending a relationship. That is not necessarily a sign of hostility. It reflects the same supervisory pressure flowing through the system. But it can slow down firms that have not built a convincing client-money operating model.
The local talent market adds another dimension. Northern Ireland has strong financial-services and technology capabilities, but specialists in payments safeguarding, client-money reconciliation and regulatory assurance are in demand across the UK. Firms that can train operations staff into control owners, rather than treating safeguarding as a niche compliance function, will be better placed to scale.
Account or insurance: a false binary
When firms review their safeguarding model, the debate often narrows to safeguarding accounts versus insurance or guarantees. The first route remains the default for many. Relevant funds are held in segregated accounts at a credit institution, with clear trust arrangements and bank acknowledgements. Done well, it offers transparency, tangible asset backing and a story that merchants and auditors can understand.
But account-based safeguarding is not frictionless. Firms must manage bank concentration risk, monitor the credit standing of safeguarding institutions, reconcile across accounts and ensure that trust documentation is not merely drafted but operable. A safeguarding account at a single bank may be simple, but it may not satisfy expectations around diversification or resilience. Multiple accounts improve resilience but increase operational complexity.
Insurance and guarantees are sometimes presented as a lighter alternative. They can offer capital efficiency and avoid some of the operational burden of holding funds in segregated accounts. However, they are not a shortcut around governance. The FCA expects firms using insurance or guarantees to demonstrate that the arrangement is robust, properly documented and capable of responding when needed. Coverage limits, exclusions, claims processes and counterparty risk all require scrutiny. In practice, the compliance burden may be different rather than lower.
For most Belfast startups, the sensible approach is not to choose an ideology but to model the options against their business. A firm with high transaction volumes and multi-currency flows may need a carefully diversified account structure. A smaller firm with predictable flows may find a guarantee arrangement workable, provided it can evidence the controls around it. What matters is that the choice is deliberate, documented and reviewed as the business scales.
A practical client-money playbook
Belfast firms preparing for tougher scrutiny should start with the basics. First, map every flow of relevant funds across entities, accounts, currencies and settlement cycles. Second, design reconciliation around the business model rather than the finance team’s existing tools. Third, secure bank acknowledgement letters and trust documentation that are specific to the firm’s arrangements, not generic templates. Fourth, build a wind-down and resolution pack that can be produced quickly and understood by an insolvency practitioner.
Governance matters as much as documentation. A named board owner for client money, a regular controls report, independent audit or assurance and a clear escalation route for breaks are all signs of a mature model. So is merchant disclosure. Firms should be able to explain to UK merchants, in plain terms, how funds are protected and what happens if the provider fails. That is not just regulatory housekeeping; it is sales support.
Turning controls into trust
Northern Ireland’s payments cluster has an opportunity to make client-money discipline part of its identity. Belfast already competes on talent, cost and access to both UK and Irish markets. It can also compete on trust. UK merchants increasingly ask hard questions about safeguarding when they choose a payments provider. A firm that can answer those questions with evidence, not reassurance, has a commercial edge.
That suggests a role for the cluster beyond individual compliance. Shared training, peer review and closer links between universities and the payments sector could build a deeper pool of client-money and regulatory-operations talent. Industry bodies and local agencies can help smaller firms understand what good looks like without pretending that one model fits all.
The FCA’s tougher safeguarding expectations will raise costs and slow some launches. That is uncomfortable for a startup ecosystem used to moving quickly. But the direction is right for a market that depends on merchant confidence. Belfast’s payments firms cannot control the regulatory timetable. They can control whether client money is treated as a back-office afterthought or as a product feature in its own right. The firms that choose the latter will be better prepared for supervision, better received by merchants and more resilient when growth arrives.