Belfast's Bid for the Payment Rails: Inside Northern Ireland's £50m Cluster Ambition
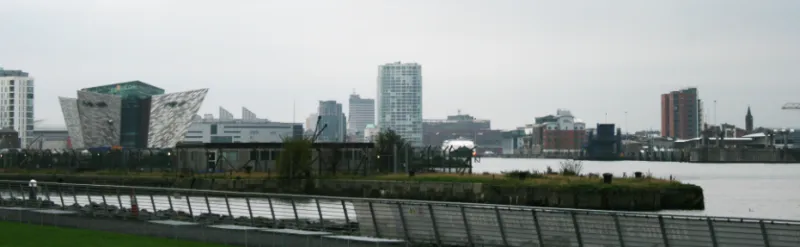
Photo: Davidwiltonone, CC BY-SA 3.0, via Wikimedia Commons
Northern Ireland's financial services sector has rarely been short of self-belief. For more than a decade, Belfast has positioned itself as a low-cost, high-skill alternative to London for compliance, operations and technology functions. Derry has quietly developed its own technology base. Yet the question now facing investors, policymakers and founders is whether that operational heritage can be converted into something more valuable: a specialist payments cluster with its own intellectual property, product companies and scaling capital.
The £50m figure is not a formal target. It is a useful shorthand for the capital, coordination and patient risk-taking that would be required to move the region from a back-office destination to a payments powerhouse. The ambition is credible, but it is not inevitable.
A cluster in the making
Belfast's financial technology ecosystem is concentrated around Titanic Quarter, Catalyst and the city centre, where a mix of indigenous firms and international captives has created a deep pool of compliance, data and software engineering talent. Companies such as FinTrU and FD Technologies have demonstrated that Northern Ireland can build businesses of genuine scale in regulated financial services. The presence of established banks and insurers has reinforced the region's reputation for operational resilience.
That base matters for payments. Modern payment businesses are not simply front-end apps; they are compliance-heavy, data-intensive and dependent on reliable infrastructure. Northern Ireland's existing strengths in anti-money laundering, know-your-customer processes, fraud analytics and regulatory reporting map directly onto the needs of payment institutions. The region does not need to invent a new skill base from scratch. It needs to recombine the one it already has.
Derry adds a different dimension. Its technology and creative industries have produced a growing pool of product and design talent, while cross-border links with Donegal and the wider north-west create a natural laboratory for euro-sterling payment flows. The city is smaller than Belfast, but its proximity to the border gives it a practical advantage in testing cross-border propositions that larger hubs rarely encounter.
Where Northern Ireland already competes
Two areas stand out: regtech and cross-border payments. In regtech, Northern Ireland's concentration of compliance professionals and its track record in financial crime prevention give it a credible claim to specialist status. In cross-border payments, the region's land border with the Republic of Ireland and its dual market access arrangements under the Windsor Framework create a genuine differentiator. Few UK regions have such direct exposure to two regulatory regimes and two currencies in everyday commercial life.
That exposure is not without friction. Post-Brexit arrangements have added complexity for firms moving money, data and staff across the border. But complexity can also be a competitive advantage. Firms that learn to navigate it can build products for a wider European market. The opportunity is to turn a compliance burden into a product category.
The London and Edinburgh benchmark
London remains the UK's payments capital by some distance. It offers proximity to the Financial Conduct Authority, the Payment Systems Regulator and the Bank of England, alongside the deepest pool of venture capital, legal expertise and payments incumbents in Europe. Edinburgh has built a credible alternative in financial services and data, supported by major banks and a strong university pipeline.
Northern Ireland cannot compete with London on scale or with Edinburgh on institutional depth. It can compete on cost, loyalty of talent and specialisation. A payments firm scaling in Belfast can access engineers and compliance specialists at a materially lower cost than in London, with lower attrition and a strong local identity. For specialist payment propositions — cross-border, regtech-enabled, compliance-heavy — that combination is attractive.
The weakness is the capital stack. London has a dense network of specialist fintech investors. Edinburgh has a growing angel and venture community. Northern Ireland's funding ecosystem is thinner, particularly at the seed-to-Series A transition, where payments companies need capital to build infrastructure, obtain regulatory permissions and win enterprise customers.
The £50m question
The £50m question is therefore less about a single cheque and more about the architecture of capital. Northern Ireland needs specialist payments investors who understand regulatory timelines, card scheme economics and the long sales cycles of enterprise payments. It needs follow-on capital so that promising companies are not forced to relocate or sell early. It needs public instruments — through Invest NI, the British Business Bank and Innovate UK — that are designed for the sector's particular risk profile rather than generic technology support.
There is also a coordination problem. The region has talented founders, supportive universities and a growing fintech network, but the connective tissue between them is still underdeveloped. A specialist payments cluster would need an anchor institution, a regulatory concierge function and a shared commercialisation pipeline. Without that, promising firms will continue to be recruited to London or Dublin.
Regulation and the skills pipeline
The regulatory environment is both an asset and a barrier. Firms in Northern Ireland operate under the same FCA and PSR regime as the rest of the UK, which provides certainty and access to the UK market. The Windsor Framework adds a distinct cross-border dimension. But regulatory authorisation is costly and slow, particularly for payment institutions and e-money firms. A more structured dialogue between the FCA, local industry and Invest NI could help founders navigate the process without lowering standards.
Skills are a related challenge. Queen's University Belfast and Ulster University produce strong graduates in computer science, law and finance, but payments-specific skills — product management, scheme rules, settlement operations and regulatory engineering — are scarce. Conversion courses, apprenticeships and industry-led training would help. So would a concerted effort to retain graduates who currently see London as the default next step.
What would tip the balance
The region does not need to replicate London. It needs to build a narrow, defensible specialism. Cross-border payments and regtech-enabled payment compliance are the most credible candidates. A specialist fund, a regulatory sandbox focused on cross-border flows, a shared platform for payment operations and a stronger industry body could together create the conditions for scale.
The £50m question is ultimately a test of patience. Payments infrastructure is not built quickly. If Northern Ireland can align capital, regulation and skills around a clear specialism, it has a realistic path to becoming a recognised payments cluster. If it spreads its ambition too thinly, it will remain a talented back office for other people's payment rails.